
Buy now, pay later (BNPL) can make a purchase feel smaller than it is. You split a payment into four installments, pay the first one at checkout, and move on. The problem shows up when you calculate your net worth: the money you still owe on those plans is real debt, even if it doesn’t appear on a credit card statement or a credit report. If you leave it out, your net worth looks better than it is. Here is how to count BNPL balances correctly.
Why BNPL Balances Belong in Your Net Worth
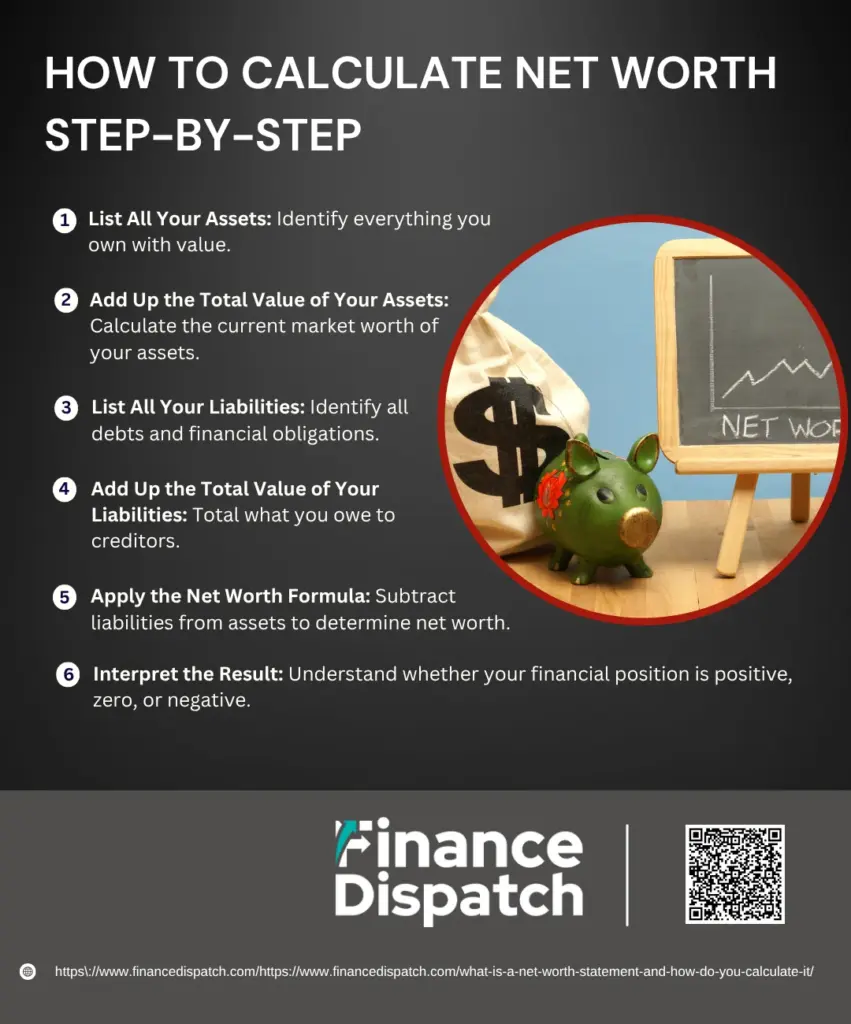
Net worth is a simple equation: everything you own minus everything you owe. Assets include cash, investments, retirement accounts, and property. Liabilities include mortgages, student loans, credit card balances, auto loans, and any other money you are obligated to repay.
A BNPL plan is a short-term loan. You received goods or services and agreed to pay for them over time. Until the final installment clears, you owe money. That obligation belongs on the liability side of the equation, whether the provider reports it to credit bureaus or not.
There is a second reason to count it. BNPL debt is easy to accumulate across multiple providers and purchases. Someone with four active plans at two different services may owe several hundred dollars without feeling like they carry a balance anywhere. Writing the number down forces you to see it.
How to Find and Total Your BNPL Balances
Start by listing every provider you have used in the past few months. Common examples include Afterpay, Klarna, Affirm, PayPal Pay in 4, and Zip, though the market changes and new services appear regularly. Some retailers also offer their own installment plans. Check your email for payment reminders and your bank statements for recurring charges to each provider, since those are the most reliable record of what you actually use.
Once you have your list, log in to each account and find the outstanding balance. Look for a section usually labeled something like “active plans,” “upcoming payments,” or “amount due.” Note two figures for each plan: the total remaining balance and the amount due in the next 30 days. The first belongs in your net worth calculation. The second belongs in your monthly budget.
The total remaining balance is the cleanest number for net worth purposes because it represents the full obligation, not just the next payment. If you cannot find a single total, add up the remaining installments for each active plan.
A simple tracking table keeps this manageable:
| Provider | Purchase | Remaining Balance | Due in Next 30 Days |
|---|---|---|---|
| Provider A | Running shoes | $120 | $40 |
| Provider B | Groceries and household goods | $75 | $75 |
| Provider C | Winter coat | $90 | $30 |
| Total | $285 | $145 |
Repeat this check whenever you update your net worth, and recalculate the total. BNPL balances change quickly because the repayment periods are short.
Treat BNPL Like Any Other Debt in Your Net Worth Calculation
List the total BNPL balance alongside your other liabilities. If you use a spreadsheet, give it its own line item rather than folding it into a credit card or “other” category. That way you can see how much of your debt is short-term installment borrowing.
If you use a net worth tracker or budgeting app, check whether it supports manual liabilities. Many apps do not automatically import BNPL accounts. Add the balance manually and update it as payments clear.
Because the repayment periods are short, there is no need to discount future installments to present value. The balances typically clear within weeks or a few months, so the difference is trivial. Most people should record the full remaining balance and move on.
Do not net the balance against the value of the item you bought. A new phone purchased with installments is not an asset that offsets the debt. Counting both sides would inflate your net worth on both ends of the equation.
Common Mistakes That Skew the Number
Counting only the next payment. Recording only the amount due this month understates what you owe. Use the full remaining balance.
Ignoring plans you forgot about. BNPL plans can be spread across several services. Search your email and bank statements for provider names and recurring charges rather than relying on memory.
Assuming zero debt when the balance is small. Even a $30 balance is a liability. The point of a net worth statement is accuracy, not tidiness.
Double-counting. If you paid a BNPL installment with a credit card and that card balance already includes the charge, make sure you are not recording the same money twice. In most cases, the BNPL balance and the card balance are separate obligations, but check how your payments are set up.
Treating the balance as an expense only. Paying an installment is a cash outflow, but the underlying debt existed before the payment. Your balance sheet needs the liability entry; your budget needs the payment entry. They are not the same thing.
How Often to Update BNPL Balances
Update the figures whenever you recalculate your net worth, whether that is monthly or quarterly. BNPL balances can shift substantially in a few weeks because the installment periods are so short. A plan that shows $200 today may be fully repaid within two months.
Whenever you update, verify that closed plans are removed and new ones are added. This is also a useful moment to check whether you are relying on BNPL for everyday purchases. If you are, that pattern may matter more to your finances than the balance itself.
Keep the Rest of Your Net Worth Calculation Consistent
BNPL is one line item. The rest of your calculation should follow the same principles: list assets at realistic values, list every debt you owe, and subtract. Be consistent about dates so that assets and liabilities reflect the same point in time. If your checking account balance is from today, your BNPL balances should be too.
Details of BNPL products, reporting practices, and provider policies change over time, and they can vary by country and provider. The core accounting rule does not change: money you still owe is a liability, and liabilities reduce net worth. Count the full remaining balance, update it when you refresh your net worth, and keep the line item separate so you can see it clearly.
Sources for Editorial Review
These are relevant pages found during drafting, not proof that any claim has been verified. Review factual statements and citations before publication.
- Editorial source lead [S1]: I thought I was savvy using Buy Now Pay Later , but… | Metro News (metro.co.uk)
- Editorial source lead [S2]: Buy Now Pay Later – Using Your Own Credit Card – Splitit (splitit.com)





